Collector and classic cars: what agreed value means and why it matters
A classic car is not a daily driver, and it should not be insured like one. Agreed value is the concept to understand.
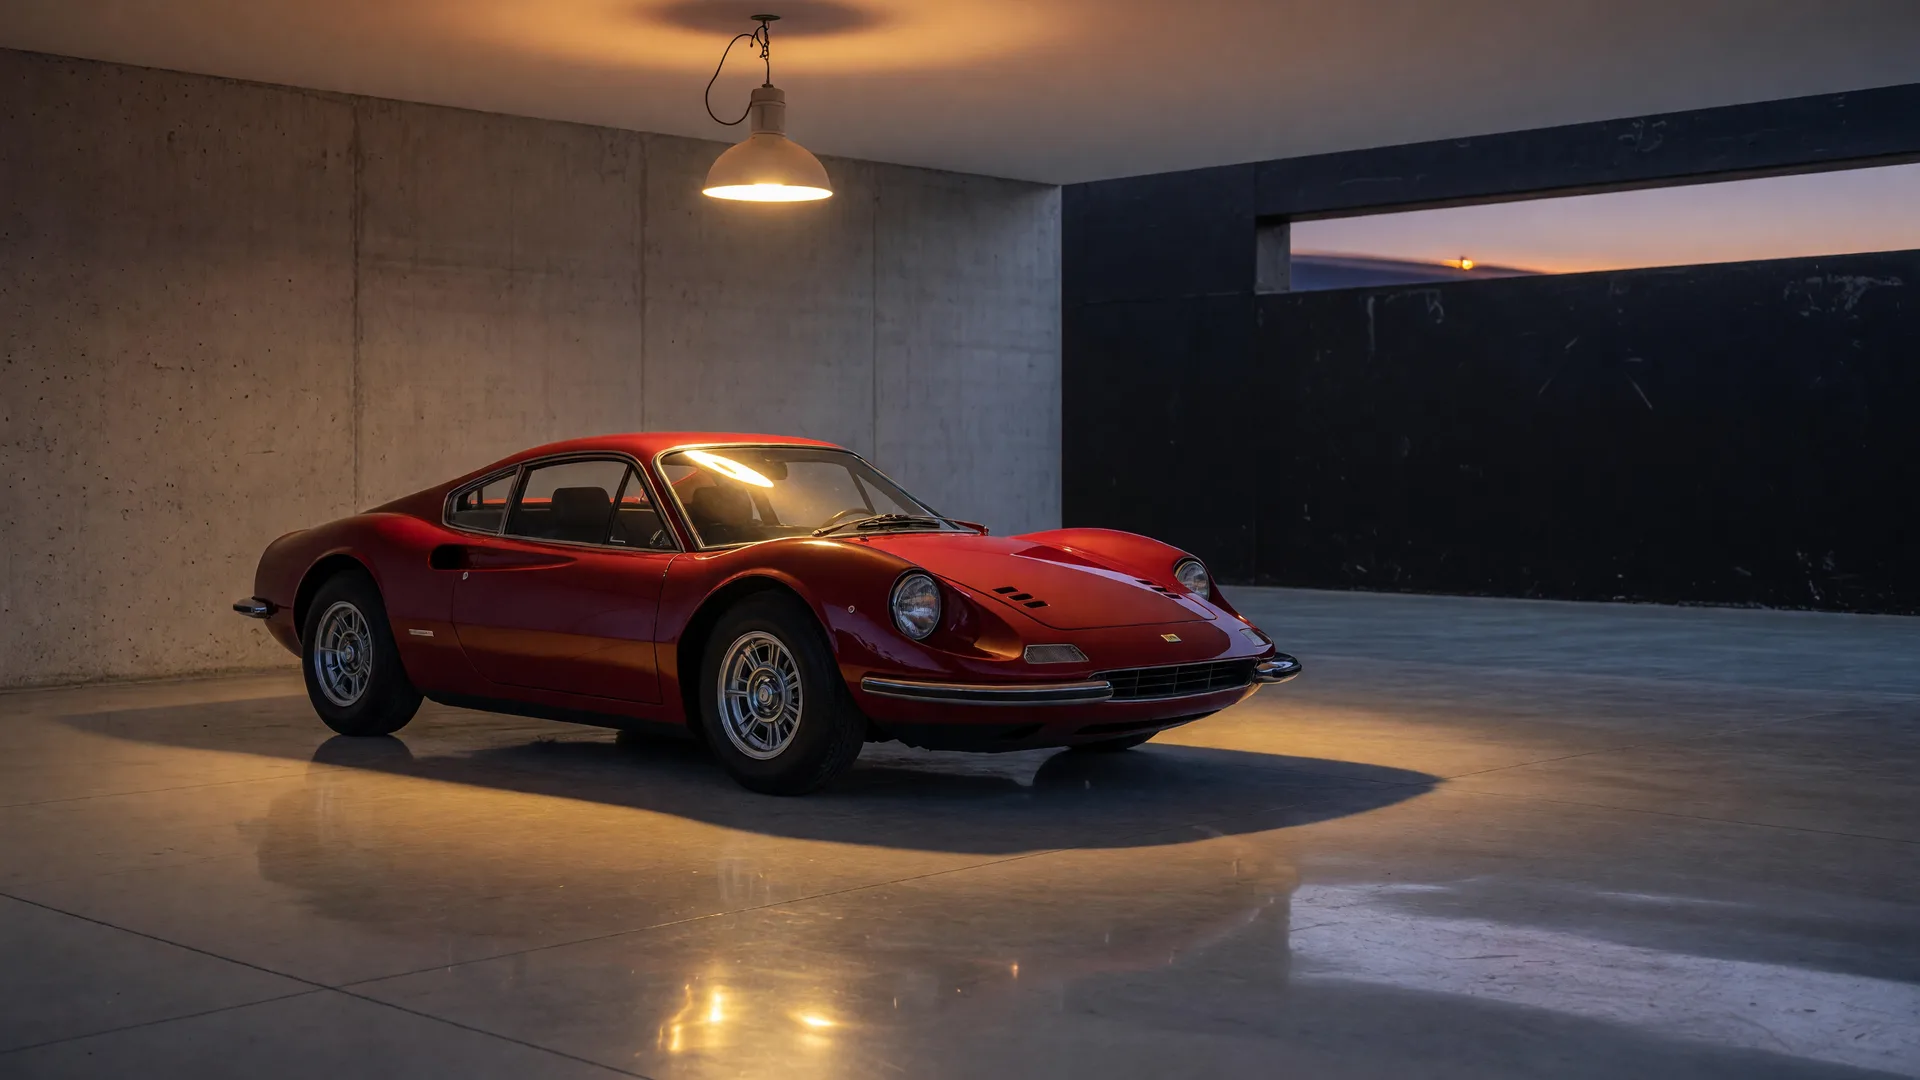
If you own a classic, exotic, or collector car, the way it is insured probably matters more than the way you drive it. A standard auto policy values a vehicle in ways that make sense for a daily commuter but can badly understate what a rare or collectible car is worth. Collector car coverage, and the idea of agreed value, is how owners protect that difference.
Why a standard auto policy is the wrong tool
Standard auto policies are built around depreciation. The longer you drive a car, the less the policy assumes it is worth, which is a reasonable assumption for most vehicles and a poor one for a car that is appreciating, rare, or meticulously restored.
For a collector car, the gap between book value and true value can be enormous. Agreed value changes the basis of the conversation: you and your advisor agree on a value for the car up front, and a covered total loss is settled on that agreed amount, rather than on a depreciated estimate.
What collector car coverage typically involves
Collector car programs are usually built around how the car is actually used: limited mileage, proper storage, and use that is not a daily commute. These structures exist because they match how enthusiasts actually keep their cars, and they tend to pair agreed value with coverage designed for the collector's world.
- An agreed value that reflects the car's true worth, not a depreciated book value
- Coverage that follows the car whether it is on the road or in storage
- Options that account for specialty parts, restoration work, and accessories
- Use patterns, like shows, rallies, and occasional driving, reflected in the terms
The conversation worth having
The value of a collector car is rarely a single, obvious number. Recent sales, restoration history, provenance, and condition all feed into it, and an advisor should help you arrive at a defensible, documented value rather than guessing.
Keep records: purchase price, restoration invoices, appraisals, and photos. When an agreed value is on the policy, the documentation behind it is what makes a claim smooth.
“An agreed value is only as good as the number you agree on. Bring the receipts, do the homework, and revisit the value as the market moves.”
Marcus Head
Common questions
Can I drive my collector car regularly?
Collector programs are typically built around occasional, enthusiast use, not daily commuting. If the car is a daily driver, a different structure may fit better. That is exactly the kind of thing a conversation settles.
How do I know what my car is worth?
A good starting point is current market data for similar cars, supported by appraisals, sales records, and restoration documentation. Your advisor can help you assemble and validate that picture.
Keep reading
More from the desk
What high-value home insurance actually covers (and what a standard policy misses)
5 min read
Umbrella insurance: the quiet layer that protects what you've built
5 min read